

Thresholds to Determine Category and Impact on Corporate Sustainability Reporting

There has been another significant development within the dynamic European Union (EU) regulatory framework concerning corporate sustainability reporting. The European Commission (EC) has officially amended the criteria for defining company and group sizes in the EU, which in turn reduces the number of companies in scope for the Corporate Sustainability Reporting Directive (CSRD).
Revised Size Categorization:
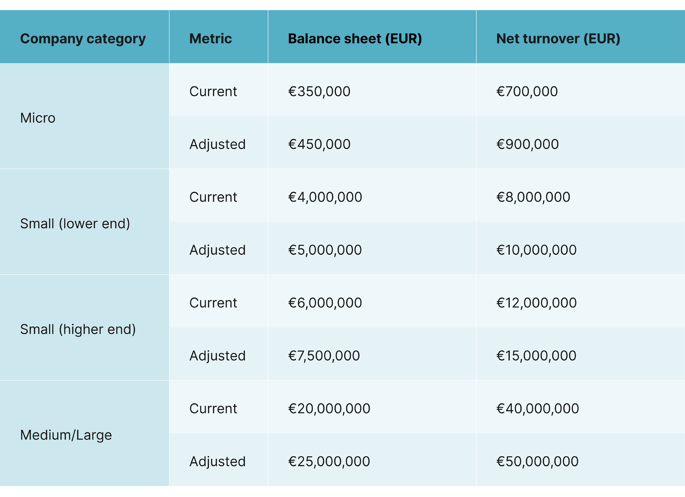
The categorization of companies or groups as "micro," "small," "medium," or "large" hinges on fulfilling or exceeding at least two of the three size criteria stipulated in the Accounting Directive1:
1. Number of employees
2. Balance sheet total
3. Net turnover
In view of the significant inflation trend during 2021 and 2022, the EC has reviewed the thresholds that relate to these criteria to assess if they imposed undue administrative and reporting burdens on certain companies. Following a review and public consultation, the EC has officially approved the increment of balance sheet and net turnover thresholds, as detailed below, while keeping the employee count intact.
Regulatory Implications
The EC enacted these changes through a Delegated Directive on October 17, 20232 and member states have a 12-month window to amend their national laws accordingly. The revised criteria will be applicable from the financial years beginning on or after January 1, 2024.
Aside from the reduction in the scope of application of the presentation, audit, and publication requirements for financial statements set out in the Accounting Directive, a crucial upshot of these modifications is the reduction in the number of companies that are in scope for the extensive sustainability reporting CSRD and the supporting European Sustainability Reporting Standards requires including reporting under Article 8 of Regulation (EU) 2020/852 (Taxonomy Regulation).3 Of particular interest would be those unlisted companies that fell into the “Large” category under the previous thresholds and now, under increased thresholds, find themselves classified as unlisted small and medium enterprises that are exempt from the CSRD mandatory disclosure requirements.
While some may perceive this change as a fair and necessary adjustment to proportionately mitigate the time and cost burdens on companies subject to the CSRD, others might contend that this narrowing scope obstructs the CSRD, and by implication Europe's climate goals, high amongst which is directing capital toward more sustainable businesses.
What Does this Mean for Your Sustainability Reporting Program?
This regulatory shift provides a reprieve for companies that felt overwhelmed by CSRD reporting challenges and now find themselves exempt. However, given the ever-increasing demand for reliable sustainability information, it is prudent for companies, irrespective of their size, to keep evaluating and enhancing their sustainability reporting strategies to meet potential future obligations and expectations.
We specifically encourage firms to review sustainability priorities, reporting strategies, and data collection systems to enable a dexterous response to future reporting obligations and, perhaps more importantly, to the rapidly evolving competitive landscape of entities that manage to turn compliance efforts into a transformative tool and, indeed, a strategic advantage.
Companies should specifically review, and revise as appropriate, their sustainability reporting strategies and obligations with their legal and financial teams, in light of these adjustments, to determine the extent to which they are impacted.
© 2023 Guidehouse Inc. All rights reserved. This content is for general informational purposes only, and should not be used as a substitute for consultation with professional advisors. This publication may be used only as expressly permitted by license from Guidehouse and may not be otherwise reproduced, modified, distributed, or used without the expressed written permission of Guidehouse.
1. Official Journal of the European Union. 2013. Review of DIRECTIVE 2013/34/EU of the EUROPEAN PARLIAMENT and of the COUNCIL. Official Journal of the European Union. June 26, 2013. https://eur-lex.europa.eu/legal-content/EN/TXT/HTML/?uri=CELEX:32013L0034.
2. European Commission. n.d. Review of Adjusting SME Size Criteria for Inflation. European Commission. https://ec.europa.eu/info/law/better-regulation/have-your-say/initiatives/13912-Adjusting-SME-size-criteria-for-inflation_en.
3. Official Journal of the European Union. 2020. Review of REGULATION (EU) 2020/852 of the EUROPEAN PARLIAMENT and of the COUNCIL. Official Journal of the European Union. June 18, 2020. https://eur-lex.europa.eu/legal-content/EN/TXT/HTML/?uri=CELEX:32020R0852.